5 Reasons Why a Land Title Loan Is Better Than a $250,000 Personal Loan
1. Superior Returns: How Land Entitlement Generates a 20–35% IRR vs. the Limited Returns from Private Loans
High-net-worth international investors with $250,000 are seeking substantial returns and wealth protection. Two models currently dominate: private credit, which offers fixed but limited returns, and land entitlement, which captures value creation prior to construction. This distinction is much more than a difference in financial structure. It represents a fundamental choice between accepting market returns or gaining access to exclusive institutional opportunities designed for sophisticated investors.
We have completed more than 130 projects since 2021, working with more than 600 investors worldwide. Our model, based exclusively on land entitlement and pre-construction value creation, consistently generates superior returns while eliminating the complexities and risks inherent in other strategies. Here’s why this approach significantly outperforms private credit for your $250,000 investment.
Private lending generally yields returns of between 8% and 12% per year. These figures look attractive on paper, but they represent a fixed return based on a stagnant foundation. Your capital does not generate additional value; it simply serves as collateral.
Land entitlement works differently. We identify undervalued properties in fast-growing markets (primarily in Texas and Florida), then we reimagine their potential use by securing zoning approvals and permits. This transformation creates significant appreciation. A parcel of land purchased for $500,000 without development rights can be worth $2 million or more once building permits are fully approved. Your investment directly captures this value creation.
With typical investment horizons of 18 to 36 months and IRR returns ranging from 20% to 35%, your $250,000 in capital isn’t tied up earning passive interest. It actively contributes to building wealth. Here’s the real difference:
- $250,000 personal loan over 5 years at 10%: total return of ~$405,000 (simple interest).
- Land entitlement: $250,000 over 2.5 years at a 25% IRR: total return of ~$640,000 (compound growth).
This $235,000 difference is not merely theoretical. It represents wealth you’ve created—or left on the table. A personal loan offers you security without creating value. An equity interest offers you both: direct participation in capital gains through a professional structure that minimizes risk.
Next step: Ask us for a personalized comparative analysis showing your exact investment scenario. We’ll show you the projected return on a $250,000 investment in our typical projects.
2. No Construction Risk: Why Investors Choose Site Preparation
Construction is when the real risks arise. Budget overruns, supply chain delays, unfavorable bids, and design changes can quickly erode margins. For a passive international investor based in Europe or the Middle East, overseeing these variables or exposing capital to them is complex and inefficient.
Our model eliminates this problem. We never invest in the construction itself. We stop at the entitlement phase. Once we have secured all the necessary permits, zoning approvals, and technical studies, we sell the project to an established developer capable of managing the construction phase. That developer pays a significant premium for a fully prepared and de-risked site.
This approach has three distinct advantages:
- You are never exposed to construction delays or cost overruns.
- The acquiring developer pays for the development rights, which means your principal remains intact, plus any capital gains realized.
- No operational involvement is required on your part during the construction phase.
Unlike traditional development, where you hold onto a project under construction for an additional 18–24 months, with land entitlement you exit the project once the legal and administrative work is complete. The developer then assumes the risk of physical construction.
Next step: Review our portfolio of completed projects. Ask to see how we structure the exit for our investors once all permits have been fully approved.
3. Short Investment Cycles: 18–36 Months vs. Long-Term Private Financing Bonds
Personal loans typically require commitments of 5 to 10 years. Your capital is tied up. During that time, your personal circumstances may change (tax reductions, strategic reallocation, emerging opportunities). You remain tied to fixed returns in an economic environment that may change radically.
With real estate ownership, your investments typically last 18 to 36 months. You realize value quickly, and then you can reinvest, diversify, or adjust your strategy based on market conditions. This flexibility is particularly valuable for international investors who manage complex portfolios across multiple currencies and jurisdictions.
Consider a real-life scenario: You invest $250,000 in a project in January 2026. By July 2027, the entitlements are fully approved. You receive your return plus the gains, totaling approximately $565,000 (25% IRR). You can now reinvest this money in a new project or another strategy. Over a 10-year period, you can complete up to 5 or 6 entitlement investment cycles, growing your capital nonlinearly through compounding.
With a personal loan, over the same period, you’ll have only one outstanding obligation due in year 10.
Next step: Request our schedule of current projects. We always have several initiatives underway at various stages, allowing you to choose the duration and return profiles that fit your schedule.
4. 100% Equity Structure: How We Avoid Debt and Protect Your Capital
Private equity is almost always backed by debt. A developer borrows 70–80% of a project’s value and uses private equity to cover the rest. This means that your capital is subordinated to senior bank debt. If the project runs into trouble, the creditors are paid first. You’re at the back of the line.
Our investment structures are 100% equity-based. We never use debt. This means that you are a direct co-owner of the land and all rights of use and entitlement. There are no senior creditors, no bank covenants, and no bankruptcy scenarios that would leave you vulnerable.
This approach provides several layers of protection:
- You own the asset directly, not a credit position.
- No risk of refinancing or interest rate volatility.
- Your capital is never at risk due to a third party’s leverage decisions.
- The projects remain financially straightforward and transparent.
During periods of interest rate volatility (such as the one we’ve experienced over the past two years), debt can become a major problem for private credit investors. Developers struggle to refinance, promised returns erode, or projects are restructured to your disadvantage. With a 100% equity structure, you are completely shielded from this volatility.
Next step: Request a copy of our corporate structure and investment documents. You’ll see exactly how we protect equity capital and how each project is legally structured.
5. Access to Over-the-Counter Transactions: The Exclusive Advantage of Our Acquisition Model
The public market for land is ineffective for high-yield opportunities. Why? Because if a piece of land has known strong development potential, commercial real estate brokers and major developers are already buying it at a premium. The profit margin has disappeared before individual investors even know it exists.
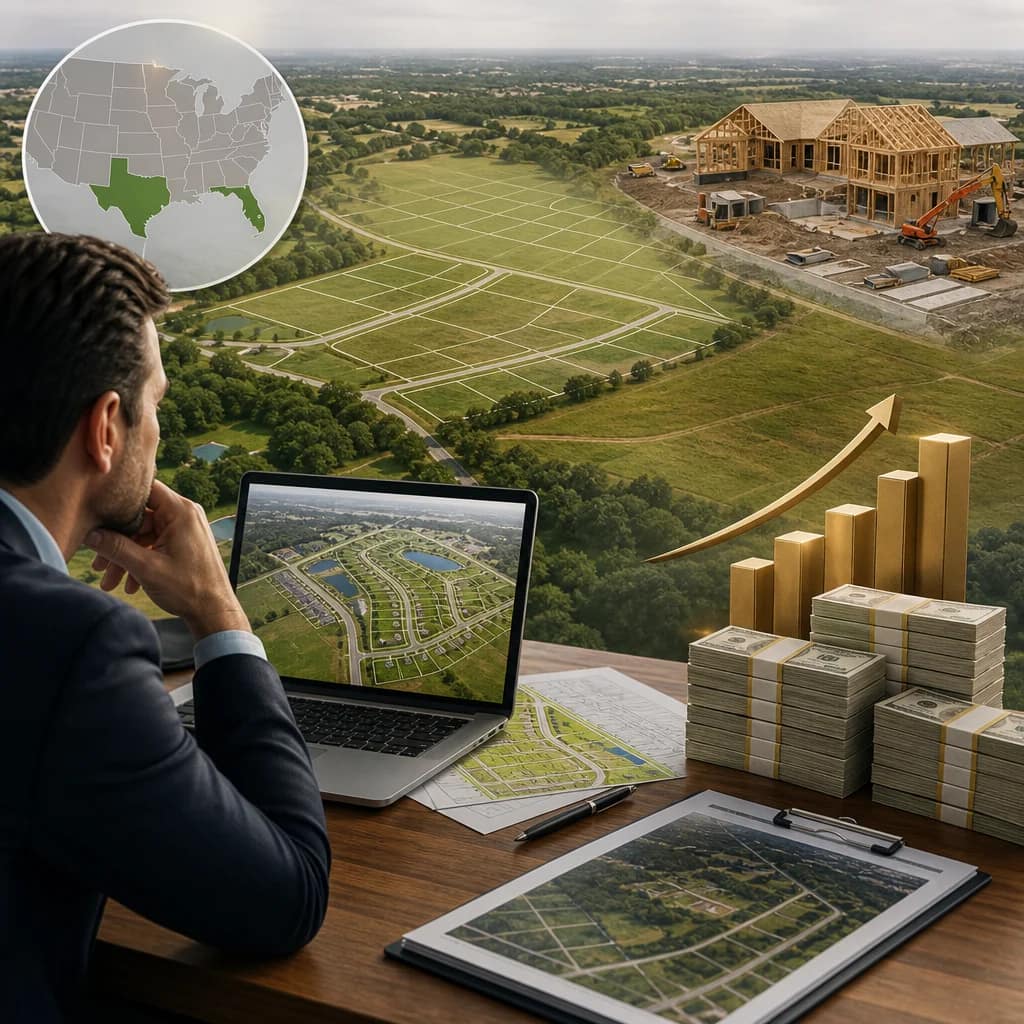
We gain access to off-market transactions through our proprietary network of real estate agents, private homeowners, and small developers in our target markets (Texas, Florida). These transactions are never listed on Zillow, CoStar, or LoopNet. They are conducted directly between the parties based on relationships and networks.
This information advantage is critical. It means we acquire land at prices well below market value, where the upside from development rights is greatest. A typical piece of land we purchase could be offered to a public developer at 1.2 to 1.5 times our acquisition price once the market recognizes its value.
For international investors, gaining direct access to these transactions is virtually impossible. You don’t have the local connections, the time to navigate the intricacies of the U.S. market, or the ability to evaluate zoning applications before they are made public. We give you access to this network as if you had a local team that had been working on this for 10 years.
Our land acquisition strategy in the United States is based precisely on this information advantage.
Next step: Request case studies showing examples of off-market transactions we have facilitated and how we identified the potential for value before the public market did.
6. Comprehensive Professional Management: From Entitlement to Exit Without Operational Complexity
Managing a real estate investment—even a passive one—requires substantial knowledge of zoning, building codes, environmental law, local permitting processes, and negotiations with government agencies. For an investor based in Europe or the Middle East, this learning curve is steep and time-consuming.
Our approach solves this problem. We handle 100% of the operational management. Our team:
- Conducted pre-acquisition feasibility studies (geotechnical, environmental, and legal).
- Hire consultants who specialize in zoning and permitting.
- Represents the project before municipal agencies and planning organizations.
- Manages the entire approval process (typically 12–24 months).
- Coordinate the project's launch by selling the approved project to a developer.
- Distribute your net returns.
You receive quarterly progress reports. You are never required to make operational decisions or interact with local officials. Your role is simply to evaluate the opportunity, decide whether to invest, and then receive your principal plus your returns.
This simplicity is particularly valued by professionally managed family offices that seek “set-and-forget” investments that require no personal involvement. Unlike private lending, where you simply wait for interest payments without any insight into the underlying project, here you have complete transparency and a dedicated team that is accountable at every stage.
Next step: Request a sample project report to see the level of detail and transparency we provide to investors.
7. Interest Rate Volatility: Why Private Lending Exposes Your Capital to Risk
The interest rate environment of 2023–2025 highlighted a major problem with private credit. When rates rise rapidly, developers who borrowed at low rates find themselves in a difficult situation. They cannot refinance without incurring drastically higher costs. Their margins erode. The economic viability of their projects weakens.
As a private credit investor, you are indirectly exposed to this instability. Developers who cannot refinance seek debt restructurings, maturity extensions, or (in the worst-case scenario) defaults. Your promised 10% return never materializes. Your principal is frozen or undergoing restructuring.
Land ownership is not subject to this dynamic. Because we do not use debt, interest rate cycles do not affect us. Our profitability does not depend on our ability to refinance. It depends on the approval of a property and its sale to a developer at a price that reflects the value created. Whether rates rise, fall, or remain stable, your investment grows according to the approval timeline, not the interest rate timeline.
For international investors managing complex portfolios, this protection against interest rate risk is invaluable. You are not at the mercy of the Federal Reserve’s decisions or bank stress tests. Your capital generates a return based on the creation of real value (approved building rights), not on yield curve arbitrage.
Next step: Learn how our projects performed throughout the 2023–2025 interest rate cycles. Request a summary of our results during this volatile period.
8. Diversified Portfolio in USD: Why Our Projects Offer Better Asset Protection
For international investors in Europe or the Middle East, the U.S. dollar serves as a safe-haven asset and a reserve currency. Building USD exposure through real assets (rather than bonds or bank deposits) is strategically important for portfolio diversification.
Private credit provides exposure to the USD, but it is abstract. You lend money that is used in a project over which you have no visibility or control. Your only right is to receive interest. If the project fails, your USD cash flow disappears.
Land entitlement gives you USD exposure anchored to a real, tangible asset: land. You directly own the land, the rights to use it, and the value created by the approval. This real asset is less susceptible to exchange rate fluctuations and inflation than a credit bond. It also generates real returns (20–35% IRR), thereby growing your USD wealth base.
Over 10 years, if you invest $250,000 in a series of land entitlement projects through LandQuire rather than in private credit, your USD wealth grows not only from fixed returns but also from geographic and regulatory value creation. That’s the difference between owning a share of U.S. growth and simply lending money to someone else who is doing so.
This approach also aligns your interests with the long-term demographic and economic trends in the U.S. real estate market, particularly in target markets such as Texas and Florida, where we focus exclusively.
Next step: Request our asset diversification analysis showing how a portfolio of land rights provides better protection in U.S. dollars compared to credit structures.
—
For international investors, the choice between private credit and real estate equity is a choice between two investment philosophies. Private credit offers security through subordination and fixed interest rates. Real estate equity offers value creation, flexibility, interest rate protection, and access to institutional opportunities that the public market never makes available.
Our 130+ completed projects and our 100% track record of securing development rights demonstrate that this model works consistently. Our 600+ investors worldwide have chosen this approach because it truly delivers on its promises: double and triple returns, short cycles, and capital protection without constructive exposure.
If you have $250,000 and are looking for real returns without the operational complexity, land ownership through LandQuire is the strategy that savvy investors choose.
Contact us to discuss your investment situation and explore our current projects.