Top 6 Strategies for Land Financial Inclusion and Entitlement in the U.S.
1. Traditional Land-Based Banking: The Passive Wait-and-See Strategy
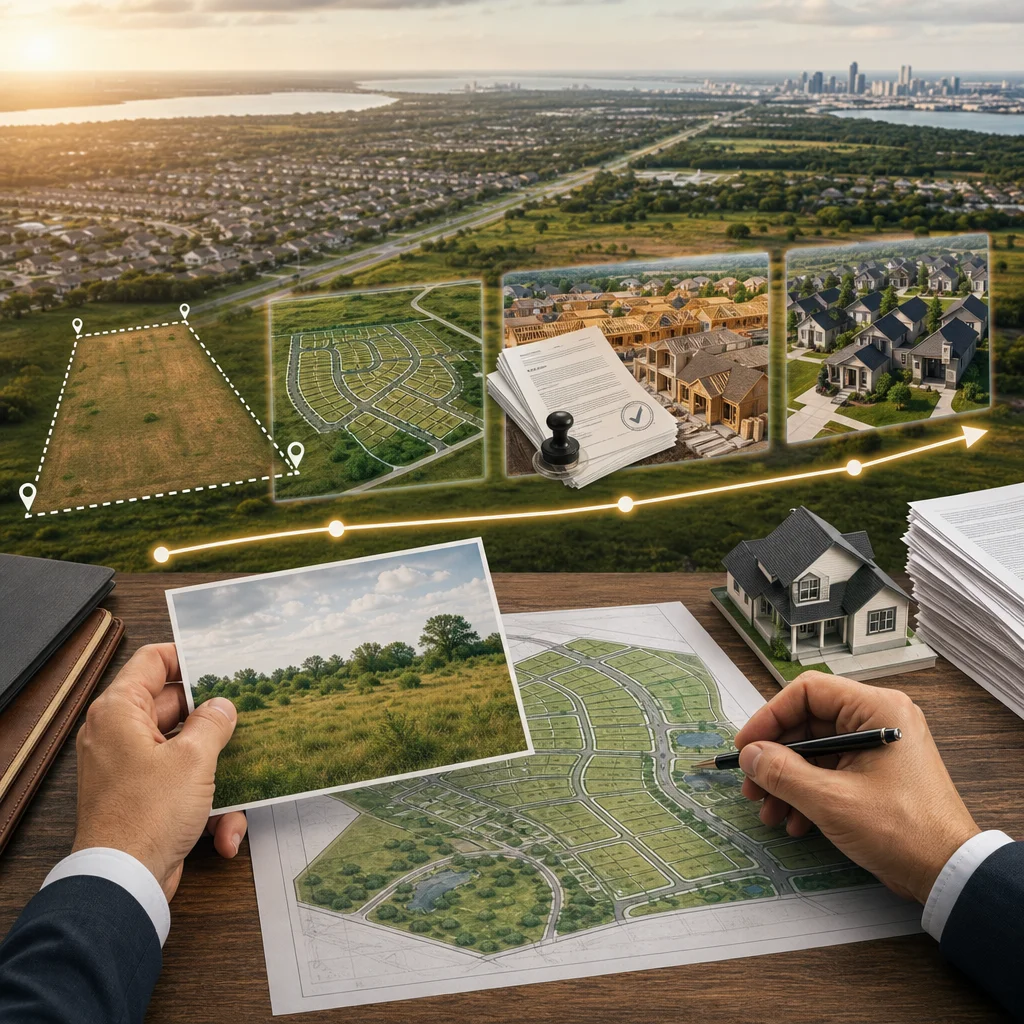
Traditional real estate investment involves purchasing a parcel of land in a growing area and waiting for its value to rise naturally. The investor buys on the open market, holds the property for several years, and then resells it at a higher price, capitalizing on regional appreciation.
This model offers clear advantages: no operational complexity, no day-to-day management, and investors benefit from local demographic and economic growth. Land itself does not depreciate (unlike buildings), making it a stable asset.
However, the average annual returns from this approach range from 3% to 8%, depending heavily on the regional market and the economic cycle. If you invest $100,000 in land in Texas expecting a 5% annual appreciation, it will take you about 15 years to double your capital. Your money remains tied up for a long time, exposed to real estate cycles, and you assume the risk of a market correction.
For investors seeking higher returns within a reasonable timeframe, this strategy falls short. That is why it works best for diversified, long-term portfolios—not as a primary source of returns.
Key takeaway: Passive banking offers simplicity but sacrifices returns and capital velocity.
2. Entitlement Strategy: Creating Value Through Permits and Zoning
The entitlement strategy transforms a simple parcel of land into an approved, build-ready project. It begins with the acquisition of raw land and then systematically adds value by securing all the necessary permits, zoning approvals, and regulatory alignments so that developers can begin construction immediately.
In practical terms: You purchase 50 acres of undeveloped land for $2 million. You work with firms specializing in zoning and urban planning to design an optimal subdivision plan (for example, 120 residential lots), prepare permit applications, finalize approvals with municipal and county authorities, and obtain the necessary signatures for registration. After 18–24 months, you sell this approved project to a developer for $3.5 million.
This approach creates value before construction begins. Developers pay a substantial premium to eliminate regulatory uncertainty and shorten their time to market. We have maintained a 100% track record in securing development permits, which means that every project we select receives the necessary approvals.
The value generated by entitlement depends on the location (Texas and Florida offer favorable conditions), the size of the project, and the proposed subdivision plan. Typical returns range from 20% to 35%+ over an 18- to 36-month period.
Key takeaway: Entitlements capture the regulatory value—the stage with the highest margin prior to construction.
3. Key Differences: A Comparison of Returns, Duration, and Risks
To illustrate the fundamental differences, let's examine a comparable investment of $100,000 applied to each of the three main approaches.
Passive investment: $100,000 → average annual appreciation of 5% → $160,000 after 10 years. Annual IRR: 4.7%. Time horizon: 10+ years. Risk: cyclical volatility, regional correction.
Entitlement only (LandQuire): $100,000 → total return of $125,000–$135,000 after 24 months (25–35% IRR). Annual IRR: 12–18%. Time horizon: 18–36 months. Risk: Regulatory risk minimized by expertise (100% track record on entitlements); short cycle reduces exposure.
Banking + Land Titling (hybrid approach): $100,000 invested in a diversified portfolio of small land titling projects → annualized returns of 20–35%+, with multiple staggered exits every 18–36 months. Annual IRR: 20–35%+. Time horizon: multiple short cycles. Risk: Diversification reduces the impact of any single project; professional management mitigates regulatory complexity.
The differences are striking. One year of returns from an entitlement strategy is equivalent to several years of passive banking. Furthermore, entitlement shortens the capital cycle, allowing capital to circulate and generate multiple full returns within the same timeframe.
Regulatory risk is the main objection to entitlement. It is mitigated by (1) local expertise, (2) the selection of favorable markets, and (3) portfolio diversification. At LandQuire, we manage this risk by personally navigating regulatory complexities and securing approvals with contractual certainty.
Key takeaway: Entitlement offers 4 to 7 times the annualized returns of passive banking, with a time horizon that is 5 to 10 times shorter.
4. Why Banking Services Alone Limit Your Returns
Real estate financing alone ties up capital for a long time without generating the added value that active management creates. Think of it as the difference between owning a raw material (land) and transforming that raw material into a finished product (land that has been approved and is ready for construction).
Suppose two investors buy the same 50-acre parcel of land in North Texas for $2 million. Investor A simply waits for the region to develop naturally. After 8 years, he sells it for $2.8 million (an annualized regional appreciation of 4%). Profit: $800,000 (4% IRR).
Investor B (LandQuire approach) purchases the same parcel and, over the course of 20 months, creates a subdivision plan for 120 residential lots, secures all the necessary permits, and then sells the approved project for $3.5 million to a developer eager to begin construction. Profit: $1.5 million (35% annualized IRR). In the same geographic area, with the same land, Investor B captures nearly twice the profit with an investment horizon five times shorter.
Why? Because developers need a pipeline of approved projects and won’t wait for zoning cycles. They pay a premium to eliminate regulatory uncertainty and shorten approval timelines. This valuation gap is invisible to passive buyers, but it is the primary source of superior returns.
Another hidden cost of passive financial inclusion: financing. If you finance a piece of land with a loan (real estate mortgage), your net returns decrease even more as interest rates rise. A 60% mortgage at an annual rate of 7% consumes 70% of moderate appreciation gains. This explains why many investors who use this strategy achieve a net return of 2–3% after financial expenses.
Key takeaway: Passive banking leaves regulatory value on the table and exposes you to financing costs.
5. LandQuire Portfolios: The Hybrid Approach Focused on Value and Performance
At LandQuire, we have developed an approach that combines the stability of land holdings with the systematic creation of value through entitlement. Our portfolios are never invested in a single project, but rather in a diversified portfolio of 3 to 8 entitlement projects spread out over time, each at a different stage of approval.
This hybrid structure offers several key advantages:
Regulatory diversification: If a project encounters an unexpected administrative complication (rare, but possible), it accounts for only 15–20% of your allocation, not 100%. The other projects continue to move forward as usual.
Continuous Capital Cycle: Rather than investing once and waiting, your capital goes through multiple cycles. A payout every 18–24 months means that a portion of your initial investment is returned every 18–24 months, freeing up capital to be reinvested or withdrawn.
Higher cumulative returns: An investment of $100,000 over four years, spread across a portfolio of four staggered projects ($25,000 each, starting 12 months apart), could generate three full exits plus a fourth currently in progress. This results in a total return equivalent to 3.5 to 4x the initial capital over four years, representing an annualized IRR of 35%+ (after fees).
Complete transparency: We regularly share progress reports for each project. You can see the permit applications that have been filed, the dates of public hearings, the approvals obtained, and the projected completion timelines.
Our project selection process follows a strict procedure: we first identify off-market land parcels in high-growth areas (primarily Texas and Florida), conduct a regulatory analysis to confirm the feasibility of obtaining the necessary permits, design the optimal subdivision plan, and then structure the investment as 100% equity (debt-free).
Key takeaway: Our hybrid approach recycles capital multiple times over a 4-year horizon, maximizing IRR while diversifying risk.
6. 100% Equity Structure: Avoiding Debt and Interest Rate Volatility
A distinctive feature of our investments is that they are structured as 100% equity, with no debt financing. This means there is no debt, no mortgage, and zero exposure to interest rate volatility.
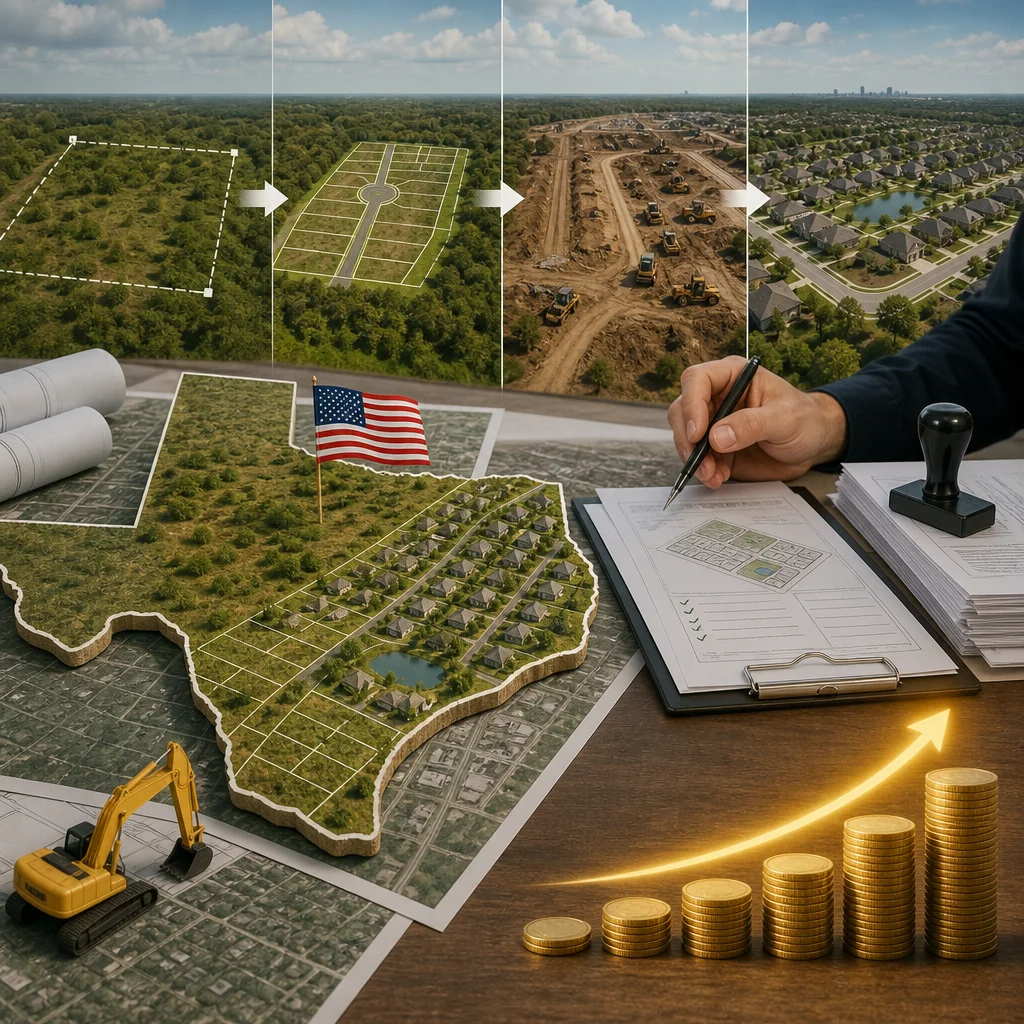
Why this is crucial: In 2024–2025, global interest rates remain high (5–7% for real estate mortgages). If you finance a project with 60% debt at 6%, each percentage point increase in the interest rate reduces your net return by 0.36% in additional interest. More importantly, a rate hike can lead to refinancing issues or unexpected margin calls.
Our investors, who are often based in Europe or the Middle East, do not need to manage these interest rate risks. Their initial investment is the final return (plus returns). The structure is simple: venture capital invested, value created through equity, then an exit at a predetermined price with a clear multiple.
This approach offers complete transparency: if you invest $100,000 in a 100% equity investment, you own your share of the project (for example, 5% if the total allocation is $2 million). You are never required to service debt if the market fluctuates. You are protected against margin calls or refinancing.
In addition, the absence of debt makes the exit process simpler and faster. Developers prefer to purchase projects with no associated debt, which shortens negotiations and reduces transaction costs.
However, there is an opportunity cost: 100% equity means we must be selective in choosing projects. We cannot finance every opportunity. This compels us to focus only on projects with a very high probability of success and superior expected returns. This is an advantage for our investors, but it also means that our pipeline of available projects is limited.
Key takeaway: 100% equity financing eliminates interest rate risk, margin calls, and financing complications; it requires a rigorous selection of projects.
7. Use Cases: Texas and Florida, High-Growth Markets
Texas and Florida are the two priority markets for land development in the United States. These states have accounted for the majority of U.S. internal migration over the past decade, with annual population growth of 1.5–2.5 percent. This growth fuels residential demand, attracts businesses, and creates a favorable environment for approving new subdivisions.
Texas (Houston, Dallas, Austin, San Antonio): These metropolitan areas are growing by approximately 300,000 residents per year. Local authorities are anticipating this growth by approving development entitlements for expansion zones. Approval times are generally short (14–20 months) because Texas encourages development. Land costs are moderate (compared to California or New York), and permitted residential densities allow for subdivision plans with 100–150 lots per typical project.
A typical use case: purchase of 40 acres outside Dallas for $1.6 million, creation of a plan for 110 lots, full approval within 18 months, sale to a developer for $2.6 million. Net profit: $1 million (IRR of over 30%).
Florida (Miami, Tampa, Orlando, Jacksonville): These regions are experiencing even faster population growth (50,000+ residents per year in the Tampa area alone). Conditions are favorable for obtaining permits, and developers are paying a particularly high premium for approved projects due to intense residential demand. Approval times are comparable to those in Texas (16–22 months).
A typical use case: purchase of 35 acres in the Orlando suburbs for $1.2 million, creation of a plan for 85 lots, full approval in 20 months, sale for $1.95 million. Net profit: $750,000 (27%+ IRR).
These two markets offer a rare combination: strong population growth + a predictable regulatory process + financially sound developers willing to pay a premium for approved projects.
Key takeaway: Texas and Florida offer the best combination of growth, regulatory efficiency, and moderate land acquisition costs.
8. Criteria for Choosing Between an Active and a Passive Strategy
Which approach is right for your investor profile? Here is a decision-making framework:
Choose passive banking if:
- Your investment horizon is 15+ years.
- Are you looking for exposure to the real estate market without active management?
- The annualized returns of 3–5% apply to your overall portfolio.
- You accept that liquidity will be low for a long time.
- You prefer administrative simplicity over higher returns.
Choose the active approach (entitlement) if:
- You're looking for annualized returns of 20–35%+.
- Your investment horizon is 18–36 months per investment cycle.
- You have $100,000 or more to invest and can tolerate a lack of liquidity for the duration of the project.
- You value professional management and want to reduce your operational workload.
- You prefer investments that are uncorrelated with long-term real estate cycles and more closely tied to regulatory value creation.
An often-overlooked factor: a preference for geographic diversification. If you’re looking to gain exposure to U.S. growth without selecting a specific city or state, a diversified hybrid portfolio (several small projects across Texas and Florida) reduces concentrated geographic risk.
Key takeaway: Passive investing is suitable for patient, long-term investors; active investing is suitable for investors seeking returns and short investment cycles.
9. Investment Horizons: 18–36 Months for Higher Returns
The typical investment horizon for a land entitlement project at LandQuire is 18 to 36 months, with an average of 24 months. This timeframe covers the entire cycle: acquisition, design, submission of applications, public hearings, approvals, registration of parcels, and sale to the developer.
Why this timeframe rather than a shorter one? Regulatory processes cannot be rushed. A public hearing is scheduled months in advance, committee approval requires a formal presentation, and the registration of the final product requires official signatures. We cannot bypass these steps, but we can manage them efficiently and accurately plan the timelines.
A typical timeline looks like this:
- Months 0–2: Acquisition, regulatory analysis, and initial design of the subdivision plan.
- Months 2–6: Preparation of application documents, engagement with local authorities, and impact studies if required.
- Months 6–12: Formal filing, administrative reviews, first public hearing.
- Months 12–18: Additional approvals (if necessary), plan revisions, second hearing, or conditional approvals.
- Months 18–24: Finalizing the terms, registering the property, and signing the final documents.
- Weeks 24–30 (optional): Marketing to developers, negotiating release prices, signing the sales contract.
This 18- to 36-month timeframe strikes a balance: long enough to complete the approval process properly, yet short enough to prevent the capital from sitting idle for years.
For investors accustomed to public stock markets (quick but volatile returns) or income-producing real estate (day-to-day management), this intermediate investment vehicle offers a “sweet spot”: higher returns without extreme short-term volatility, and professional management without the complexity of day-to-day operations.
Key takeaway: An 18- to 36-month timeframe allows for rigorous regulatory compliance while enabling capital to be recycled several times over a 5- to 7-year period.
10. Transparency and Track Record: How to Evaluate Real Estate Opportunities
Before investing your capital in a real estate strategy, you should evaluate two factors: the team’s track record and the transparency of the investment process.
Track Record: At LandQuire, we have completed more than 130 projects since 2021 with a 100% track record in securing development permits. This means that every project we have selected and presented to investors has received final approval. None have failed to meet regulatory requirements.
This figure is significant because it reflects (1) a rigorous upfront screening process (we reject 95% of the opportunities we identify), (2) in-depth local regulatory expertise, and (3) disciplined management of the approval process.
Ask any property manager these questions:
- What percentage of your projects receive the expected funding?
- What is the average return after expenses?
- How many projects have exceeded their projected investment horizon?
- How many investors return for subsequent funding rounds?
Transparency: We share monthly progress reports for each project. You can see the applications filed, hearing dates, approval statuses, and comments from the authorities. No vague estimates—just documented facts.
In addition, we outline the structure: what is your ownership percentage, what are the fees (typically 15–20% of net proceeds), and what is the exit strategy (direct sale to a developer, with a target price range)?
Finally, assess the portfolio’s diversification. A manager who invests all your capital in a single project is taking on a disproportionate amount of risk. A manager who spreads your investments across 3–5 projects staggered over time provides natural protection.
Key takeaways: Verify the actual track record (100% entitlements), request transparency regarding progress reports, and insist on portfolio diversification.
For further reading: Texas vs. Florida guide.